By a community association industry contributor.
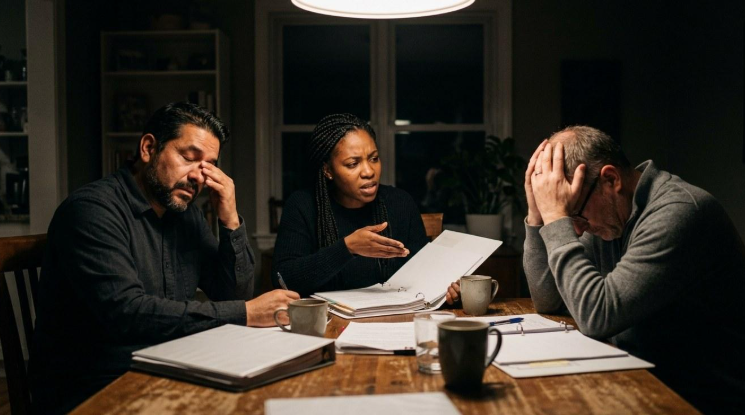
It often starts with a simple spreadsheet and a few dedicated volunteers. But as a community grows, so does the work. What was once a few hours a month becomes a second job. It’s filled with late-night calls about plumbing, tricky talks with vendors, and the tough job of making sure everyone follows the rules fairly. The risk of burnout for volunteer board members is high, but the money and legal risks are even higher. A poorly managed savings fund or an unfair rule decision can put the whole community at risk.
This is the turning point where many communities look for professional help. Moving from a do-it-yourself approach to a professional partnership is a big step. It means handing over daily tasks, money management, and future planning to one of the many specialized homeowners association property management companies available. This isn’t just about passing off tasks. It’s about putting a professional system in place to protect home values and help the board meet its legal duty to protect the community’s money. The field is growing because these challenges are becoming more common.
Quick answer: An HOA should switch from self-management to professional management when the legal, money, and daily tasks become too much for the volunteer board to handle with their time, skills, and comfort level with risk. This change protects the HOA from liability and makes sure it is run fairly and follows all the rules.
What’s inside
- How Do You Calculate the Real Cost of Self-Management?
- What Are the Signs Your HOA Is Ready for Professional Help?
- How Should You Structure a Management Contract?
- Frequently Asked Questions
How Do You Calculate the Real Cost of Self-Management?
The true cost of self-management includes the value of volunteer time, the money risks of not following rules, and the drop in home values from poor upkeep.
Many boards see volunteer work as free, but this misses the hidden cost of their time. The work of managing a community is a professional job with a real market value. According to the U.S. Bureau of Labor Statistics, the median yearly pay for community association managers was $69,990 as of May 2025. When a volunteer board member spends 10 hours a week on HOA tasks, they are donating over $17,000 worth of their time each year. This isn’t just a number; it represents time that could be spent on their own jobs, with their families, or just enjoying the community they are trying to serve.
Beyond the cost of time, there are real money risks. A volunteer treasurer without a strong accounting background might make a mistake with the savings fund. This could lead to a surprise bill for all homeowners when a major repair is needed. Not enforcing rules fairly can lead to lawsuits, while missing a deadline for city paperwork can result in fines. These are not just what-if situations; they are common problems that can cost a community thousands of dollars and create major arguments among neighbors.
❝ A useful exercise is to have your board members track their time for one month. Log every phone call, email, meeting, and visit with a vendor. When you multiply that time by what a pro would charge, the “cost” of self-management becomes much clearer. It often shows that the association is running on a donation of personal time that can’t last forever.
Finally, the need for this professional skill is growing. The U.S. Bureau of Labor Statistics projects that jobs for community association managers will grow by 4 percent between 2025 and 2035. This shows that running an HOA is getting more complicated, from dealing with new environmental rules to managing fancier features like pools or gyms. When a volunteer board can no longer keep up, the result is often delayed repairs and last-minute decisions, which can lower home values for everyone in the community.
What Are the Signs Your HOA Is Ready for Professional Help?
The key signs are when board members are always tired and stressed, money issues are getting complicated, and it’s hard to handle big repair projects or arguments between neighbors.
Volunteer board members are the heart of many communities, but they only have so much time and knowledge. When board meetings are filled with frustration instead of getting things done, it’s a clear signal. If board members are spending more than ten hours a month on HOA tasks, quitting because of stress, or struggling to find new volunteers, the do-it-yourself model probably isn’t working anymore. This burnout isn’t just a personal problem; it leads to slow decisions, poor follow-through, and fewer people getting involved.
Money management is another key turning point. An HOA with a simple yearly budget and few late payments can often be managed with basic accounting software. However, the situation changes when the association needs to:
- Do a professional study to plan for big future repairs (like a new roof).
- Manage a complex budget with many different spending categories.
- Take formal steps to collect unpaid dues.
- Create official financial reports for banks or people looking to buy a home here.
When these tasks are beyond the money skills of your volunteer treasurer, the chance of expensive mistakes and surprise bills goes way up. Professional managers can handle these complex jobs, keeping the HOA financially healthy and compliant. Groups like the Community Associations Institute (CAI) offer certifications for managers, showing they have a basic level of knowledge in HOA finance and rules.
❝ The switch often happens when the board realizes it’s spending 90% of its time reacting to daily problems instead of planning for the future. If your meetings are spent arguing about lawn rules instead of planning for major repairs 10 years from now, you’ve lost sight of the big picture.
Use this checklist to see where your community stands. If your HOA is in the “High Risk” column for two or more areas, it is a strong sign that you need professional help.
| Symptom | Low Risk (Self-Management OK) | High Risk (Consider Professional Help) |
| Board Workload | Under 5 hours/month per member. | Over 10 hours/month; members resigning. |
| Financials | Simple budget, few late payments. | Needs a reserve study, more late payments. |
| Projects | Minor landscaping, routine repairs. | Major roof/siding replacement, paving. |
| Disputes | Occasional neighbor complaints. | Sending violation letters, facing legal threats. |
| Compliance | Stable local and state laws. | New laws that affect the HOA. |
In the end, the decision is about managing risk. When the possible cost of a legal mistake, a bad contract, or a money shortfall is greater than the monthly fee for a management company, the choice becomes a clear part of your duty to protect the community.
How Should You Structure a Management Contract?
A strong management contract should have three key parts: a clear list of duties, an easy-to-understand payment plan, and a way to end the contract if needed.
The biggest reason for problems between an HOA and a manager is an unclear list of duties. The agreement should be more specific than general terms like “financial management.” It should list out the exact tasks. For example, does “financial management” include preparing monthly reports, paying bills, collecting late dues, and working with the CPA for the yearly audit? Each of these should be spelled out. The contract should also explain how and when you will communicate, such as who your main contact is and how quickly they should reply to the board.
Next, look closely at the payment plan. Most contracts use one of two models:
- All-Inclusive: A single, flat monthly fee that covers a long list of services. This makes budgeting easy but may include services your community rarely uses.
- A La Carte: A lower base monthly fee with extra charges for certain tasks. These can include things like preparing documents for home sales, attending special meetings, or managing big projects. This model can save money for communities with simple needs, but surprise problems can make costs add up fast.
Before signing, ask for a full list of all possible fees. Compare that list to your HOA’s activities over the past year to get a better idea of the total yearly cost under an a la carte plan.
❝ One of the most important, but often missed, contract terms is about banking. The contract must state that all the HOA’s money, for both daily operations and savings, will be held in bank accounts that belong to the HOA. The management company should be a signer on the accounts, but never the owner. This is a key step to prevent the company from mixing your money with theirs and makes sure the board always controls the HOA’s money.
See Also: The Welder Everyone Recommends: A Reality Check
Finally, every contract needs clear rules for ending the agreement. It should define the terms for ending the contract both “for cause” (if one side doesn’t do its job) and “for convenience” (if the board just wants to make a change). A “for convenience” clause is important so you have options. Look for a fair amount of warning time, usually 60 to 90 days, which gives you enough time to find a new manager without causing problems for the community.
Frequently Asked Questions
What does an HOA management company actually do? A management company’s duties usually fall into three areas. Administrative tasks include handling communication with residents, keeping records, and organizing board meetings. Financial services cover preparing budgets, collecting dues, and working with accountants for tax filings. On-site services include regular property inspections, managing maintenance contracts, and overseeing repairs to common areas.
Can an HOA board legally hire a management company? Yes, the board’s power to sign contracts for the association is almost always spelled out in the HOA’s official rules, such as the bylaws. As part of your duty to act in the community’s best interest, the decision to hire, the selection process, and the final vote should be recorded in the official board meeting minutes. This creates a clear record for all homeowners.
Why hire a manager instead of continuing to volunteer? Besides saving time, a professional manager provides a neutral third party to enforce the rules. It is often hard for a resident to give a violation notice to their next-door neighbor, but a manager can do it fairly based on the community’s rules. They also have a network of trusted and insured workers, which can save your board a lot of time and risk when getting quotes for big projects.
Is professional management legally required for an HOA? In most cases, it is not a legal requirement, but it can be something you really need to do. Some HOA rules, especially for large communities built by a developer, may require a professional manager. For very small associations, like a duplex or a four-unit building with very few shared areas, self-management is often effective and cheaper.
What is the difference between a property manager and a community association manager? A regular property manager usually works for a single owner to manage rental units. They focus on issues between landlords and renters, collecting rent, and leasing. A community association manager works for the whole community. Their focus is on governance, managing common areas, enforcing rules, and giving advice to the volunteer board on behalf of all owners.
Moving from Volunteer Labor to Professional Governance
The decision to hire a management company is a key moment for any homeowners association. It shows the community is moving from a casual group of volunteers to a more formal non-profit business with valuable property to protect. The warning signs, board member burnout, money matters getting more complicated, and major repair projects, are not failures. They are normal signs that a community is growing and becoming more valuable. This changes the main question from “Can we afford the monthly fee?” to “Can we afford the risk of making a legal or money mistake on our own?”
Ultimately, the choice comes down to the board’s duty to protect the community. A board’s main job is to make wise choices that protect and increase the value of everyone’s homes. A professional manager is a tool to help them do that job. They bring expertise in following rules, handling contracts, and managing money that volunteers are not expected to have. The goal is not to replace the board, but to make it stronger. By handing off the daily tasks, board members can finally focus their energy on what they were elected to do: focus on the big picture and build a stronger community for the long term.